Women & Financial Independence: Building Wealth That's Truly Yours
Financial independence for women isn't a trend. It's a necessity that remains an unaddressed concern for many women.
Financial independence for women isn't a trend. It's a necessity that remains an unaddressed concern for many women.
This doesn’t happen because women don't care about their financial futures. Careers may be interrupted for family or military service, or financial management may get delegated to a partner by default. And, unfortunately the financial services industry was built with a different client in mind. All these factors make it easy for a woman's individual financial security to quietly fall behind the household's financial picture.
For couples who have merged finances it can be difficult to see the difference between household finances and individual financial security. A household can appear financially healthy while one partner (often the woman) has little in her own name. In some cases she has no retirement account, little or no individual credit history, and limited knowledge of where accounts are held or how to access them. That gap doesn't become visible until something changes. A deployment. A health crisis. A divorce. A death. Then suddenly the financial ground beneath her feet isn't what she thought it was.
For military spouses, the obstacles they face are specific and significant. PCS moves interrupt careers, which makes it harder to build retirement assets. Deployments require solo management of the household. The financial decisions made in a partner's name such as TSP elections, SBP choices, or insurance coverage have direct consequences for a spouse's future security.
For women business owners, the challenge looks different, but the risk is similar. Everything goes into the business. Retirement savings wait for a better year. Present tax decisions have a significant future impact. Personal financial planning gets deferred until the business is more stable. And the future self who needs that foundation pays the price for the current self's priorities.
At Clear Insight Wealth Management, these stories are personal. As a women-owned, fee-only firm, we built our practice specifically to serve clients who have been underserved by the traditional financial planning industry. We love serving women in military families and business ownership who have been managing extraordinary financial complexity without adequate support because they resonate with our own stories.
Here is what financial independence actually looks like and what building it requires.
Retirement Savings in Your Own Name
This is the foundation of everything else, and the place where the gap is most common and most consequential.
A woman who relies entirely on her partner's retirement savings has no individual retirement security. If the relationship ends through divorce, that pool of assets may be divided. The division of assets in such situations is rarely straightforward, and the outcome is rarely what either party expected. If her partner dies first, survivor benefits may or may not be adequate. If the partner becomes incapacitated, the retirement savings are still there, but access and management become complicated.
Women live an average of five to six years longer than men. The statistical likelihood that a woman will spend a meaningful period of her later years managing finances alone, whether through widowhood, divorce, or a partner's cognitive decline, is high. Building retirement savings in your own name, consistently over time, is the most meaningful path to minimize the hardship of that reality.
For military spouses who are not currently employed or employed part-time, the spousal IRA is one of the most underused financial tools available. This account allows a non-working or part-time working spouse to contribute to a Traditional or Roth IRA based on the working spouse's earned income. The limits are up to $7,000 in 2026, or $8,000 for those age 50 and older. This contribution goes into an account in the spouse's name. It grows for the spouse's retirement. It belongs to the spouse regardless of what happens to the marriage or the service member's military career.
The Roth IRA is often the right choice for military spouses whose household is in a moderate tax bracket. Contributions are taxed now at today's rate, and withdrawals in retirement are completely tax-free. With decades of compounding potential and the flexibility that Roth accounts provide, a spousal Roth IRA started early and funded consistently can become a meaningful source of independent retirement security.
For women business owners, retirement savings often compete with business reinvestment, and the business almost always wins. This is understandable. However, this strategy can create significant difficulties later in life. The SEP IRA and Solo 401(k) available to self-employed individuals are not just retirement tools. They are tax reduction tools that make contributing to personal retirement savings more financially efficient than keeping that money in the business. Every dollar contributed to a SEP IRA or Solo 401(k) reduces taxable income by that same dollar. Seen in this light, the retirement account isn't competing with the business, it's part of the financial strategy for running it.
Your individual credit history is irreplaceable.
Individual Credit History
Your individual credit history is irreplaceable. Joint accounts and a partner's strong credit history alone don't build it for you. A woman who has relied entirely on household credit or a partner's accounts may discover that she has very little credit history of her own when she most needs it.
The scenarios where individual credit history matters are more common than most people expect: divorce, death of a spouse, a sudden change in household finances, the desire to make an independent purchase, or starting or expanding a business. In any of these situations, a credit file that reflects your own history of borrowing and repaying rather than your household's is the foundation of financial independence.
For military spouses, this gap is particularly common. Frequent moves, career interruptions, and reliance on a partner's income can make individual credit building feel unnecessary. The household has good credit. The finances are being handled. Why does it matter?
It matters because that credit profile belongs to your partner, not to you. If your partner's name is on the accounts and yours isn't, their credit history isn't yours.
The practical steps are straightforward: open and maintain at least one credit card in your name only. Use it regularly for purchases you would make anyway. Pay the full balance every month. Keep your utilization low. Monitor your individual credit through annualcreditreport.com. If you have no individual credit history at all, a secured credit card is a low-risk starting point that builds a record efficiently.
For women business owners, personal and business credit deserve equal attention. A strong business credit profile, separate from your personal credit, creates financing options and protects your personal assets from business liabilities. Many women business owners build strong personal credit and neglect business credit entirely, or vice versa. Both matter.
Understanding the Complete Financial Picture
In many households, one partner manages most financial decisions by default. As a result, decisions about investments, insurance and estate documents become largely invisible to the other spouse. Rarely is this a deliberate exclusion. Rather, it is a natural division of labor that seems reasonable until something changes.
For women who are not the primary financial manager in their household, this gap in understanding creates an invisible vulnerability. A military spouse who has deferred all financial management to a service member may face sudden, overwhelming responsibility during a deployment, a medical emergency, or a death. In consequence, she may be left without the knowledge, the access, or the legal authority to navigate it.
Understanding the complete financial picture doesn't require taking over financial management. It just requires knowing enough to act if you need to.
That means knowing where all accounts are held and how to access them. It means knowing what insurance is in place, what it covers, and how to make a claim. It means understanding the TSP, including what the balance is, how it's invested, what the Roth vs. Traditional election means for your family, and what the SBP election means for you specifically as a surviving spouse. It means having your name on at least some financial accounts, not just as a beneficiary, but as an account holder with independent access rights. And it means being an active participant in financial planning conversations.
This is not a criticism of households where one partner handles more of the financial management. It's simply a recognition that financial knowledge is a form of protection. And that protection should be available to both partners, regardless of who holds the primary financial management role.
A financial plan that doesn't account for your goal isn't a complete financial plan.
Financial Planning That Reflects Your Goals
Traditional financial planning was built around a set of assumptions that don't reflect the lived reality of most women: a continuous career with steady income growth, a partner who dies first and leaves a comfortable inheritance, a retirement that begins at 65 and lasts a predictable number of years. Those assumptions tend to underserve women.
Women face career interruptions that traditional retirement projections don't account for. Military spouses may restart their careers multiple times across a decade of PCS moves. With each move, absorbing the cost of lost seniority, lost retirement contributions, and lost Social Security credits. Women business owners often have years with variable or reduced income during the early stages of building a business. These realities require a financial plan that was designed with them in mind from the start, not retrofitted to accommodate them.
Women also face a longer retirement horizon. A woman who retires at 62 may have 30 or more years of retirement ahead of her. The investment strategy, withdrawal sequencing, and income planning for a 30-year retirement look materially different from the planning built around a 20-year horizon. A financial plan that doesn't account for longevity isn't a complete financial plan for most women.
What women-centered financial planning actually includes:
Retirement projections built on a realistic life expectancy rather than an average one.
Income replacement strategies that account for career gaps and re-entry, not just continuous earnings history.
Insurance planning that addresses the financial consequences of a partner's death or disability — including a clear-eyed evaluation of whether the SBP election is adequate coverage for a military spouse's needs.
Estate planning that ensures financial security regardless of relationship status.
An ongoing planning relationship with an advisor who asks about your goals, not just the household's goals.
At Clear Insight Wealth Management, this is the approach we take with every client. Not because our clients ask for it, but because it's the best way to build a plan that actually works.
Building Wealth Through and Beyond Military Life
Military life creates real financial obstacles for spouses. This is simply true, and it's worth acknowledging directly rather than minimizing.
PCS moves disrupt careers, often at critical junctures. Each new duty station requires rebuilding a professional network, sometimes restarting a licensing or certification process, and adapting to a job market that may or may not value the skills she holds. Deployment creates extended periods of single-income household management with elevated stress and elevated expenses. The cumulative effect on a military spouse's career trajectory, retirement savings, and financial independence can be significant.
But military life also offers many great financial opportunities.
BAH and BAS are allowances that can free up income for savings, when housing and food costs are managed strategically. The VA loan benefit allows military families to build home equity without a down payment, even across multiple PCS moves with multiple properties over a career. SCRA interest rate protections reduce debt costs during deployment. Military OneSource provides free financial counseling specifically designed for military families. And the service member’s TSP is one of the best retirement savings vehicles in existence, particularly under BRS with government matching contributions.
The mindset shift that matters most: military spouse financial planning isn't something that begins after service ends. It's something that happens now, with the tools available, in a way that creates options for every season of military life and builds a foundation of individual financial security that outlasts the uniform.
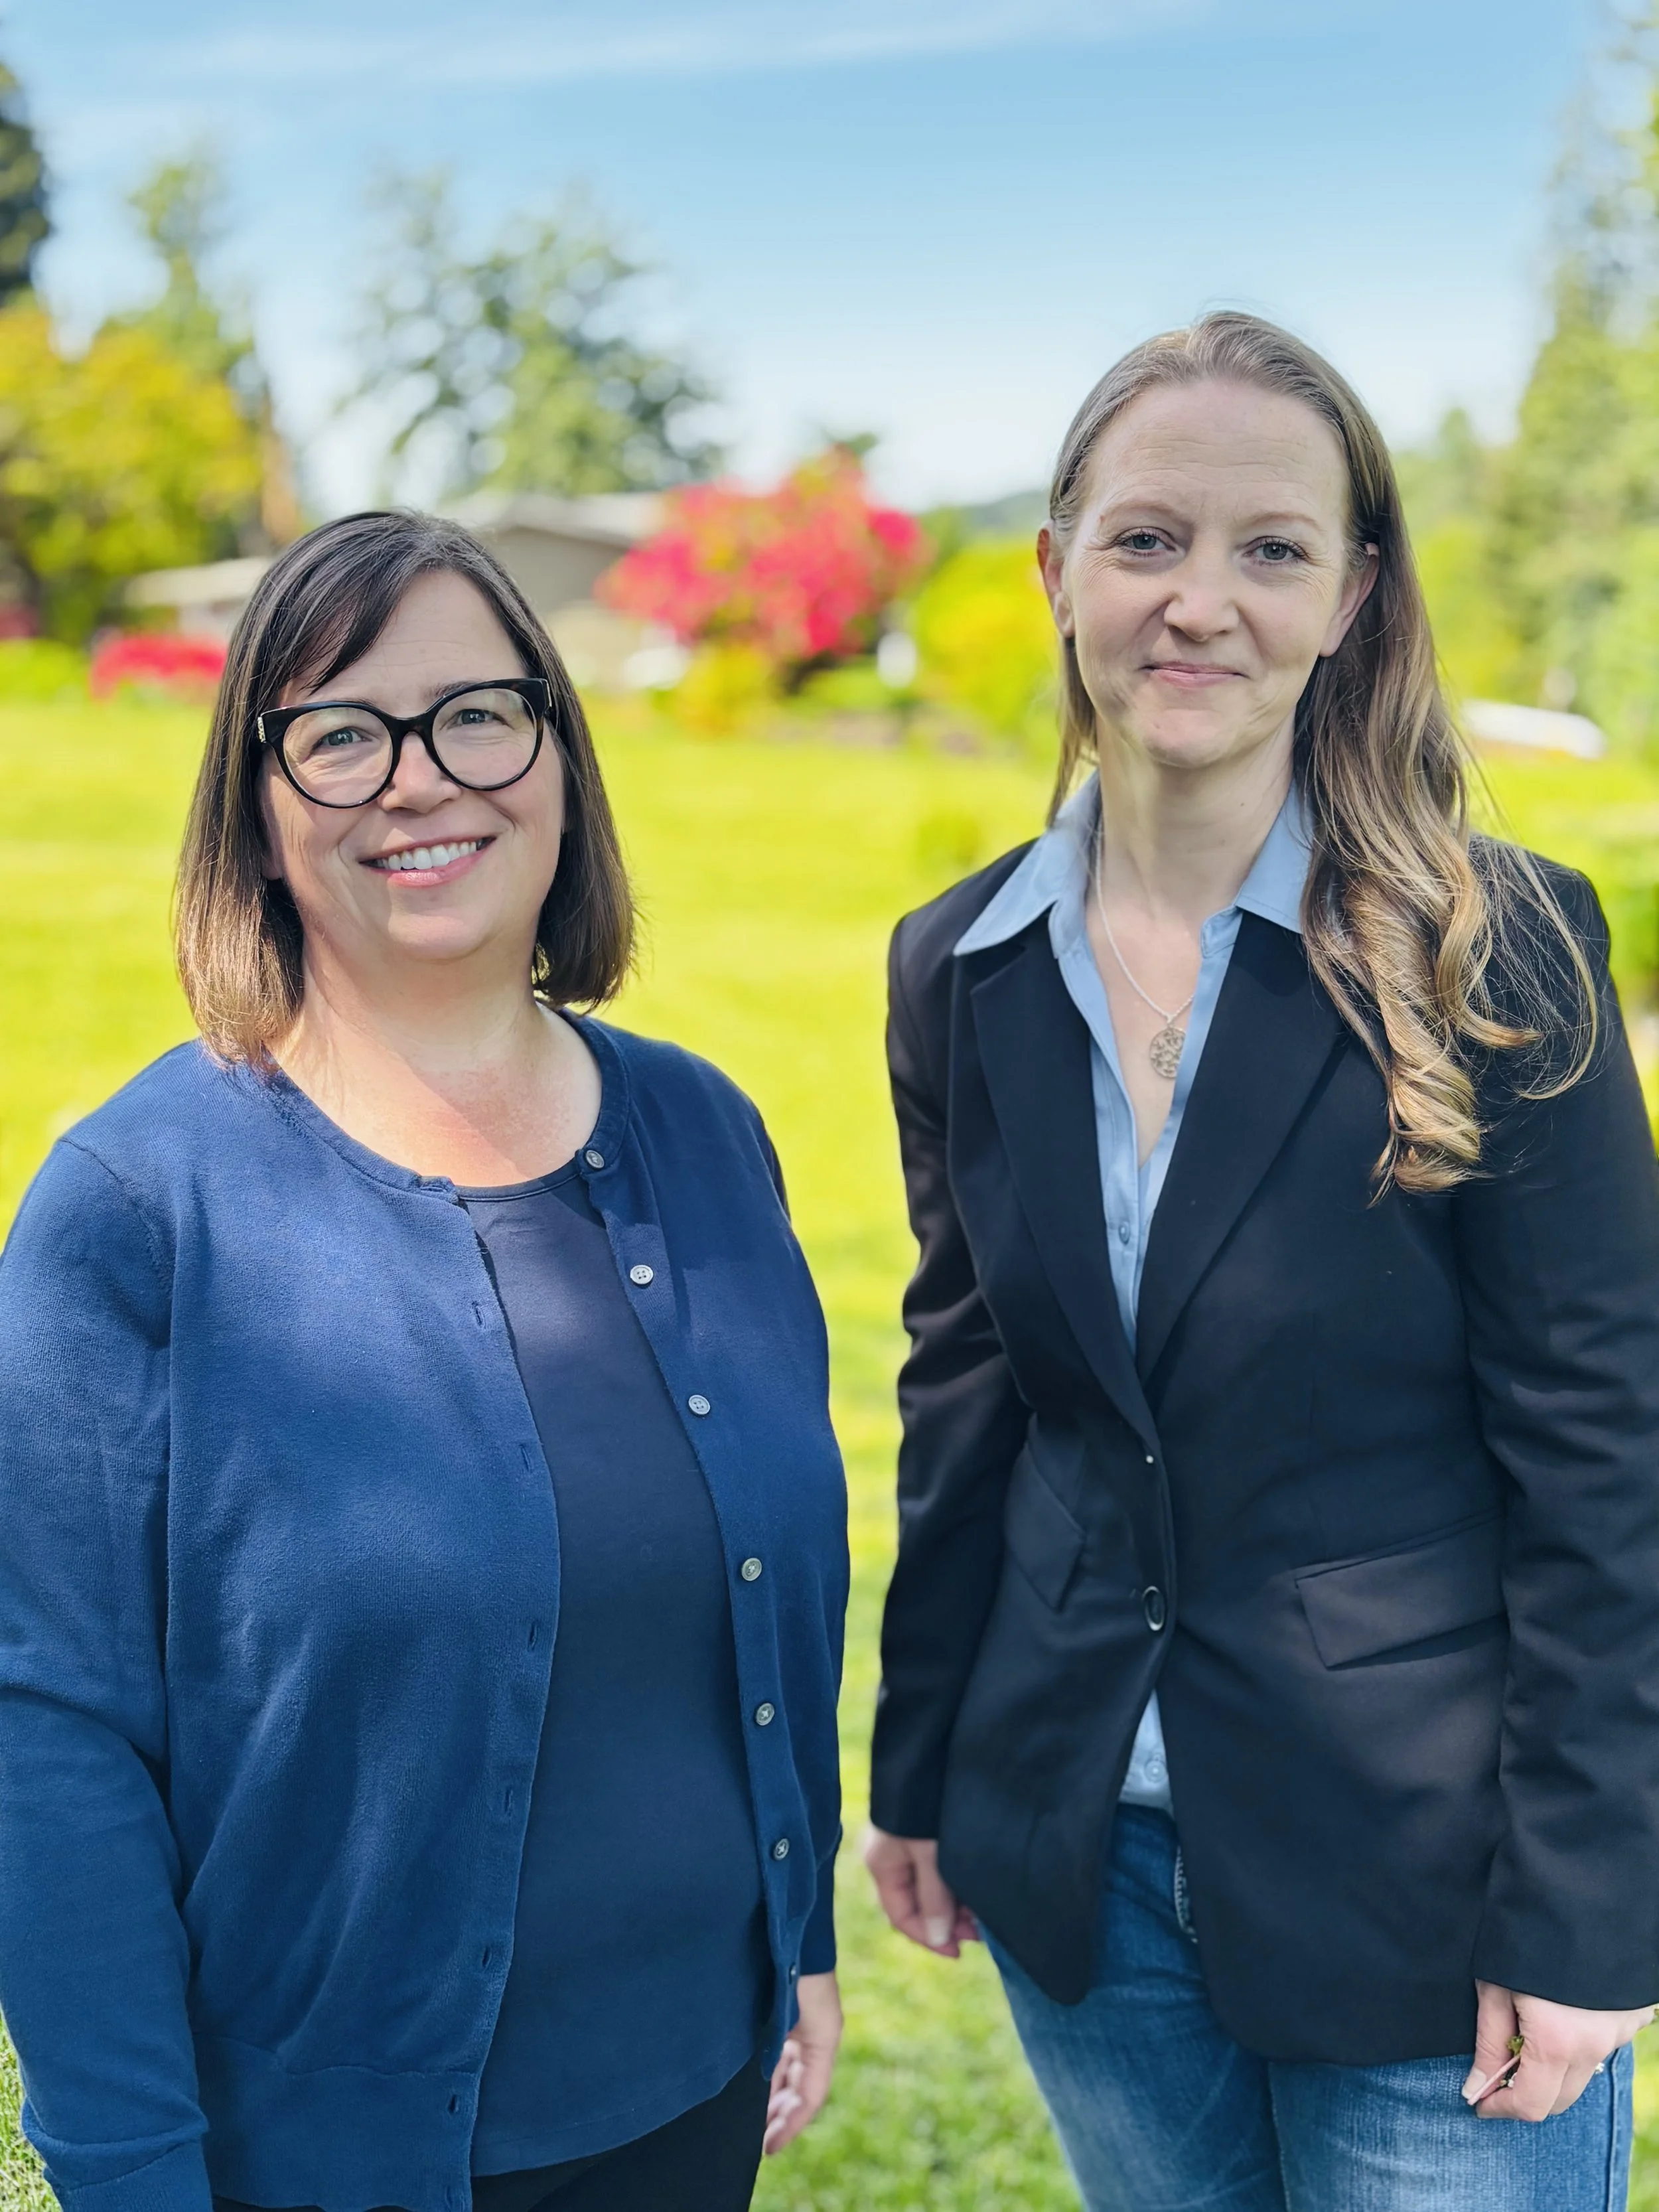
We built this firm because we believe that every person deserves financial advice that sees their complete picture.
A Note From Clear Insight
We built this firm because we believe that every person deserves financial advice that sees their complete picture.
For military spouses, that means an advisor who understands what PCS moves cost, what deployment does to a household, what the SBP election means for your future, and why your individual financial security matters as much as the household's.
For women business owners, it means an advisor who understands variable income, self-employed retirement options, and the particular challenge of building personal financial security while pouring everything into building something you believe in.
We are a women-owned, fee-only firm. We earn no commissions. We have no products to sell. Our only objective in every client relationship is honest, clear guidance built around your life, not a model built around someone else's assumptions about what your life should look like.
If this resonates with you, we'd love to start a conversation.